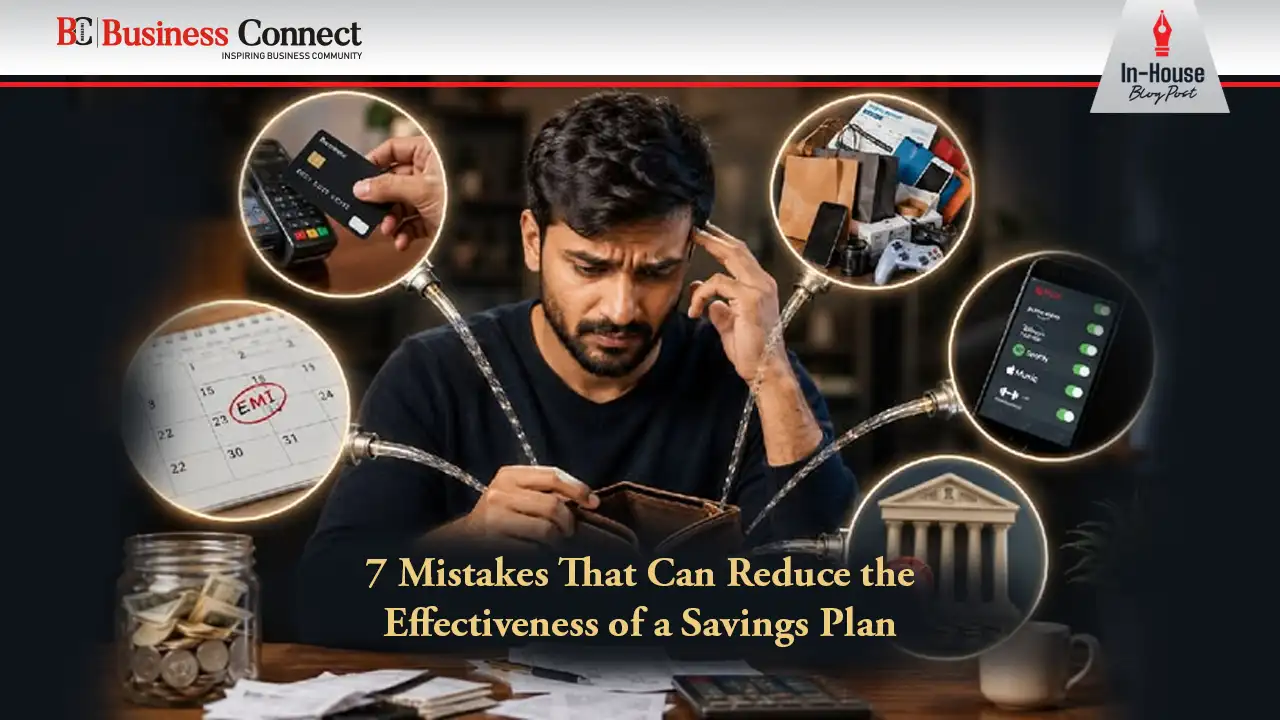
7 Mistakes That Can Reduce the Effectiveness of a Savings Plan
Saving money regularly can create a sense of financial progress, but consistency alone does not always lead to the outcome you expect. The choices you make along the way can influence how well your financial strategy supports your future needs.
Choosing a savings plan requires more than setting aside money and waiting for the policy to mature. Understanding what you are committing to can help you decide what fits your financial priorities.
Let’s explore the mistakes that can affect your savings strategy and the factors you can consider before making a decision.
What Can Prevent Your Savings Plan From Meeting Your Goals?
Your savings strategy needs to work within your financial circumstances and future plans. Certain decisions may appear convenient initially but could affect how effectively the arrangement serves its intended purpose.
1. Saving Without a Clear Financial Goal
Not having an objective with regard to your finances at the beginning makes it hard to establish how much money you need and how long you need to invest. Your objectives can include paying for college, buying a house, planning for retirement, or meeting other future financial needs.
2. Choosing a Premium That Does Not Fit Your Budget
The premium you select should be manageable alongside your regular income and financial commitments. Choosing an amount that puts excessive pressure on your budget could make it difficult to maintain payments over the policy term.
Review your monthly expenses, existing commitments, and future financial obligations before deciding how much you can comfortably allocate towards your savings plan.
3. Focusing Only on the Maturity Amount
The maturity amount can be an important consideration, but it does not provide the complete picture. Depending on the plan, you may also receive life protection, death benefits, income benefits, or other features.
Look at the overall benefit structure before making a decision.
4. Choosing an Unsuitable Policy Duration
The policy duration determines how long you remain invested and when you become eligible for the policy benefits. Choosing a duration without considering your financial timeline can make savings plans less suitable for your circumstances.
Consider your expected investment period and choose a duration that aligns with how long you are comfortable keeping your money committed.
5. Overlooking Liquidity Needs
Long term savings require commitment, but your financial circumstances can change. An unexpected expense or change in your priorities could create a need for access to funds.
Before selecting among savings plans, examine the liquidity options available under the policy.
6. Treating Tax Benefits as the Main Reason to Invest
Tax benefits can form part of your evaluation for the savings plan you are opting for, but they should not become the sole reason for choosing a savings arrangement. Your financial objective, affordability, policy term, benefits, and protection needs also deserve attention.
A broader assessment can help you select a plan based on its overall suitability rather than a single potential advantage.
7. Failing to Review Your Plan Over Time
Your financial priorities may change as your income, responsibilities, and future goals evolve. A plan that once worked for you under certain conditions may now need revision according to changes in your financial situation. Keep revisiting your plan and examining its key points, including the nomination.
As your financial goals evolve, you may also need to reassess how you plan to use your savings in the future. A Systematic Withdrawal Plan Calculator, also known as the SWP calculator can help you estimate potential withdrawals and understand how a systematic withdrawal approach could fit into your broader financial planning.
How Can You Compare Different Savings Plans Before Making a Purchase?
Looking beyond the headline maturity benefit can give you a more complete view of savings plans. Several factors can help you compare plans based on their potential returns, protection, flexibility, and overall cost.
| Comparison Factor | What to Check | Why it Matters |
| Guaranteed and Non Guaranteed Benefits | Check which benefits are guaranteed and which depend on future performance or other conditions. | Helps you set realistic expectations about the benefits you may receive. |
| Death Benefit Structure | Understand how the death benefit is calculated and what your nominee may receive during the policy term. | Shows the level of financial protection provided alongside savings. |
| Policy Loan Facility | Check whether a policy loan is available, along with its eligibility conditions and effect on policy benefits. | Can help you assess the liquidity available if you need funds during the policy term. |
| ULIP Charge Structure | Review the different charges applicable to a ULIP and understand their impact on your investment. | Helps you evaluate the overall cost before choosing a ULIP. |
| Additional Riders | Compare the riders available, their costs, and the additional protection they provide. | Helps you determine whether additional coverage is relevant to your financial needs. |
Build a Savings Strategy That Fits Your Future
Financial decisions become more meaningful when they reflect where you want to be, rather than only what looks attractive today. Taking time to assess your priorities and understand the terms can help you approach a savings plan with greater clarity.
Leading providers like Kotak Life Insurance, which reported a 99.5% claim settlement ratio for FY 2025 to 2026, can be considered as part of your evaluation when you are looking for a savings solution that aligns with your financial objectives. The right choice can give your financial planning greater direction and help you move forward with confidence.
Add Business Connect magazine to your Google News feed